Wall Street Is Counting on Nvidia to Keep the AI Party Going
Nvidia’s earnings will test Wall Street’s confidence in the AI boom.

By David Uberti and Krystal Hur
Mon, Aug 24, 2026 8:23pm 3 min
3 min


Nvidia’s earnings will test Wall Street’s confidence in the AI boom.
3 min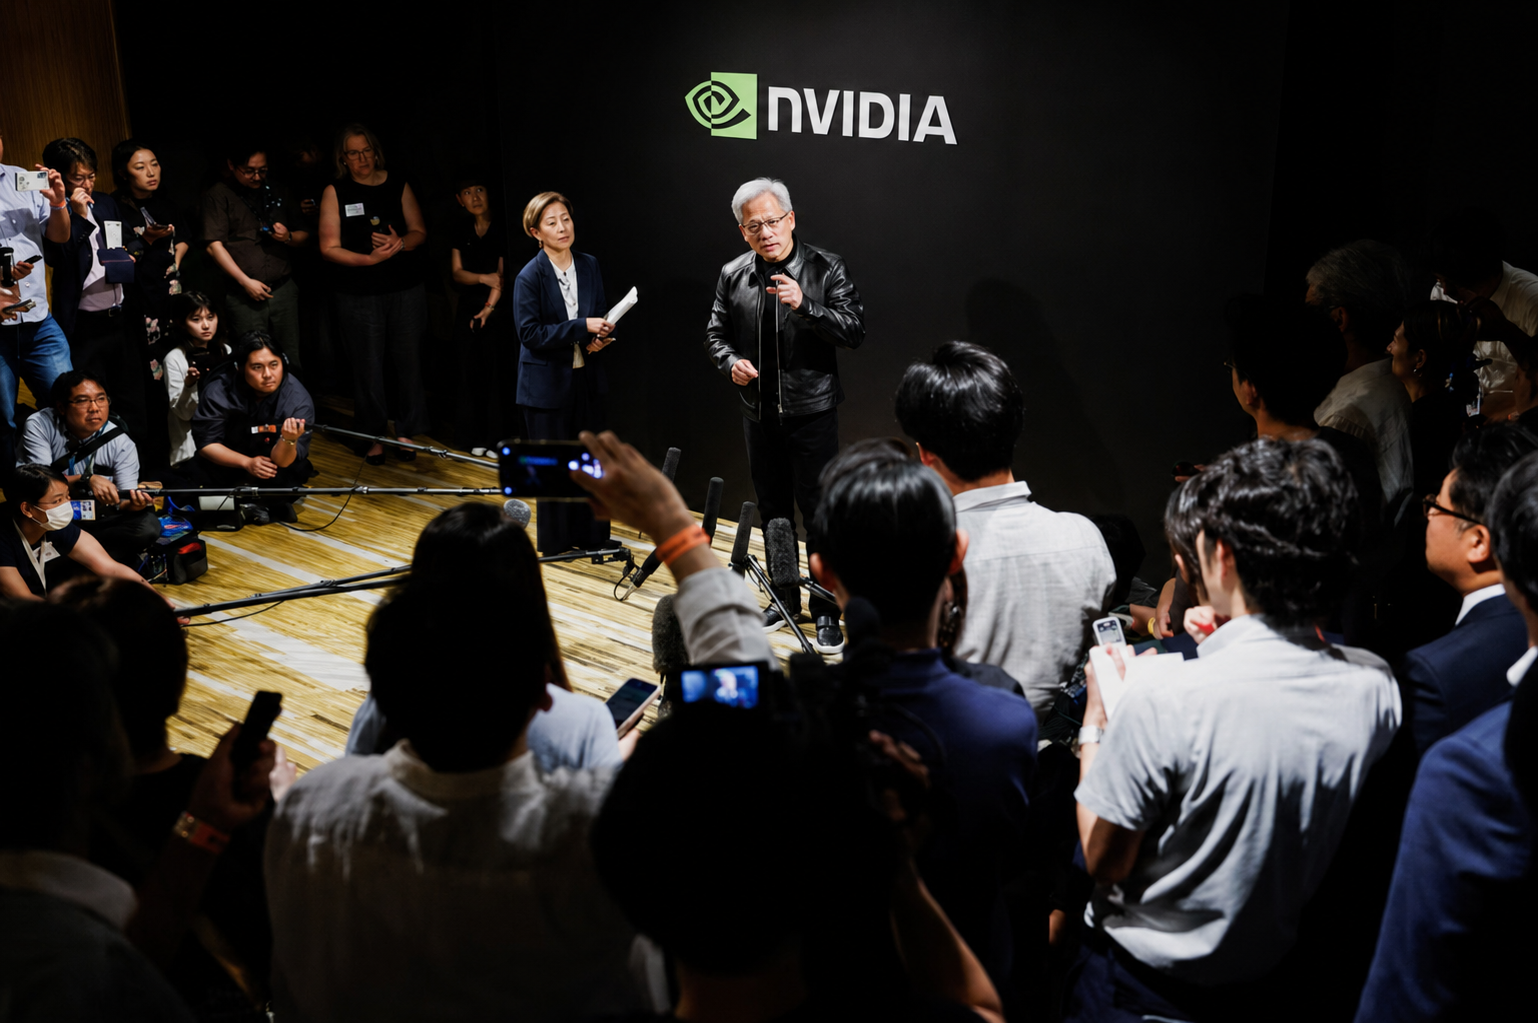
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Chip makers are fighting to assure investors that the artificial-intelligence boom is racing forward. Wall Street might not believe it until Nvidia’s NVDA -0.98%decrease; down pointing triangle Jensen Huang says so.
When Huang steps up to the mic for his company’s earnings call Wednesday, he will have the world’s attention. What he says about Nvidia’s present will preview the future of AI, dictate the path forward for a tech-crazed stock market and influence an American economy increasingly tethered to hopes that the boom won’t go bust.
The $5 trillion chip maker has provided the key building blocks for AI since the launch of ChatGPT in 2022 set off a race for dominance among OpenAI, Anthropic and established Silicon Valley giants. Now, as Nvidia backstops sprawling data-center projects and an exotic money pipeline to boost chip demand, the company’s influence is arguably bigger than ever.
But there are signs of trouble ahead. Political pushback to AI is growing. A bond selloff propelled borrowing costs to their highest levels in years. The hyperscalers that include some of Nvidia’s key customers—once cash-printing machines—are relying more on debt. OpenAI recently told investors its revenue rose by a tepid 18% in the second quarter while its losses deepened.
Nvidia is increasingly stepping in to shore up potential weak points across the market. Earlier this month, the company teamed up with six of Wall Street’s biggest firms on a $500 billion AI-financing plan, pledging to backstop lending to customers that can’t afford its chips otherwise. The chip maker last week also took a stake in Cloverleaf Infrastructure, which arranges power for data centers, and struck a $6 billion deal with startup Poolside aimed at developing a powerful open-weight AI model.
After watching shares in other chip makers and the so-called Magnificent Seven tech companies swing wildly in recent months, Wall Street is hoping Nvidia can beat expectations—again. The countdown is on.
“It’s kind of becoming more and more like the World Cup final than the Super Bowl at this point,” said Brian Mulberry, chief market strategist at Zacks Investment Management. “It’s just gotten to be that big.”
The company has smashed analysts’ earnings estimates for each of the 14 quarters since the AI boom kicked into high gear. Nvidia posted 210% annual growth in net income in its last three-month period, according to FactSet, making Wall Street’s 126% projection look pedestrian.
Expectations for a blowout second quarter have risen rapidly over the course of this year. All Nvidia will have to do to beat this target: outrun 95% annual earnings growth to more than $51.5 billion. Analysts project the chip maker will report record sales of $92 billion for the period, up from a forecast of $78 billion at the start of this year.
In July, big-tech earnings sparked volatility. Concerns about runaway capital spending spread across the sector after Alphabet’s and Tesla’s results, driving a $890 billion wipeout that contributed to the unwind of hedge fund Situational Awareness. Microsoft posted the largest one-day gain in market capitalization by any company, ever, after a quarter proving that it could still show investors the money. SpaceX rocketed higher after a record-breaking initial public offering, only to see $1 trillion in value evaporate.
Surging memory prices and borrowing costs have fueled fears that those and other companies will be unable to keep plowing more money into supplies including Nvidia chips. Shaia Hosseinzadeh, founder of OnyxPoint Global Management, has recently bought dips in AI-infrastructure stocks when Wall Street has strained to absorb massive debt issued by Silicon Valley.
“The macro data is really quite robust,” he said. “Of course, there’s a level at which everything breaks.”
Investors have kept pumping money into the AI trade despite concerns around chip consumers—and to the benefit of chip producers. That is why Nvidia’s outlook for semiconductor demand could send ripples through counterparts such as Micron Technology and Sandisk, developers of the data centers in which their chips reside, and a supply chain of power producers, contractors and other specialists that underpin the globe-spanning AI build-out.
“We joke internally that we’re all Nvidia analysts now,” said David Lefkowitz, head of U.S. equities at UBS Global Wealth Management.
The irony is that investors have tended to sell Nvidia stock immediately after blockbuster earnings, with shares falling each trading session after its four past quarterly reports. Some are betting that will be the case this time around, too.
The options market is pricing in a 5.3% swing, higher or lower, in Nvidia shares during the session following earnings, according to Option Research & Technology Services. That is higher than the 4.8% average move in Nvidia’s stock over the last 12 months after the company reports quarterly results.
In recent days, some of the most actively traded Nvidia options have been put contracts tied to the stock falling from its Friday value of $214.75 to $205 and $210 apiece, according to Cboe Global Markets data. Put options give the right to sell a stock by a set price and typically represent a bearish wager.
Many analysts remain optimistic. Frank Lee, global head of tech hardware and semiconductor research at HSBC Global Investment Research, recently raised his price target for Nvidia shares to $360 from $325, citing, among other things, Nvidia’s strategic partnerships with suppliers and its role as a top contributor to open-source AI.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.